Bangkok; October 2026: The International Monetary Fund (IMF) and the World Bank Group (WBG) Managements has released the “Bangkok Blueprint”, a high-level framework developed in coordination with the Bank of Thailand that aims to help countries prevent, detect, and address the growing threat of cyber-enabled fraud in digital financial services.
Released today during the 2026 IMF–WBG Annual Meetings in partnership with the Thai authorities, the Blueprint sets out 12 key considerations to help countries identify vulnerabilities and develop comprehensive, coordinated responses. By promoting a more coherent approach across sectors and jurisdictions, the Blueprint sees to strengthen trust in digital financial services and support their continued contribution to growth and inclusion.
Digital finance has expanded access, innovation, and efficiency, but it has also enabled fraud
to occur at greater speed, scale, and sophistication. Cyber-enabled fraud is increasingly linked to transnational organized crime and is ranked by INTERPOL as among the most threatening crimes globally, alongside drug trafficking and money laundering.
Vitai Ratanakorn, Governor of the Bank of Thailand has said on the occasion of the release: “Cyber-enabled fraud has become a global challenge that no country or institution can tackle alone. The Bangkok Blueprint reflects our shared commitment to strengthen cooperation, build trust, and promote a safe and inclusive digital financial future for all”.
Kristalina Georgieva, the Managing Director of the IMF has said: “Trust is the foundation of every financial system. As digital finance expands, countries must work together to combat cyber-enabled fraud and preserve confidence in the technologies that support growth and inclusion”.
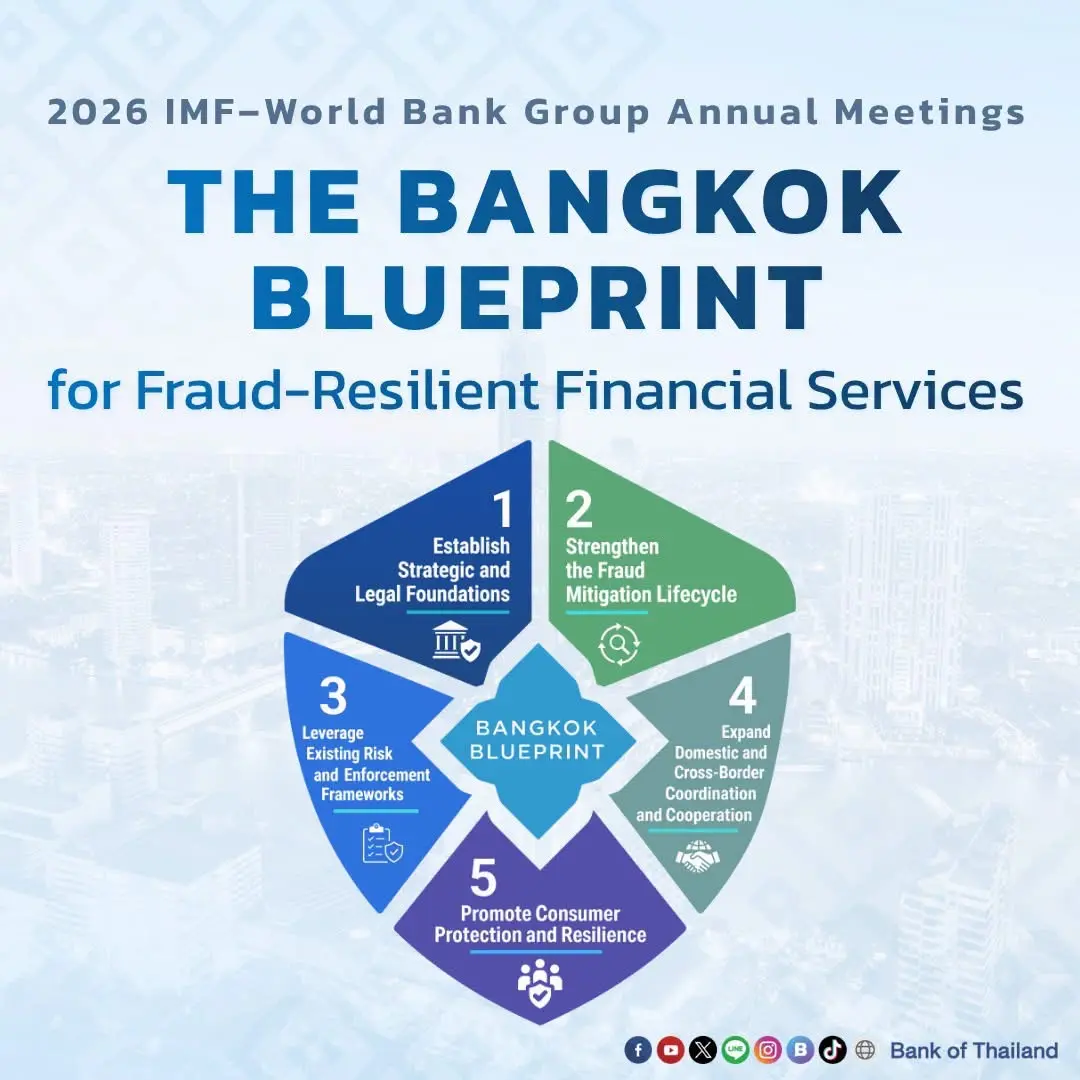
The Bangkok Blueprint is organised around five pillars:
·establishing strategic and legal foundations;
·strengthening the fraud-mitigation life cycle;
·leveraging existing risk-mitigation and enforcement frameworks;
·expanding domestic and cross-border cooperation;
·promoting consumer protection and resilience.
“Digital financial services can be a powerful driver of economic opportunity, jobs, and financial inclusion in developing economies. Strengthening protection against fraud is essential for ensuring that people can use these services with confidence and fully benefit from the opportunities they create”, said Anshula Kant, Managing Director and World Bank Group Chief Financial Officer.
Recognising that fraud schemes often involve social media, digital platforms, e-commerce,and telecommunications networks, the Blueprint emphasises clear accountability and timely cooperation across the public and private sectors, both domestically and across borders. It encourages countries to tailor the 12 considerations to their legal, institutional, and market conditions.
“As digital finance becomes increasingly interconnected, our response to fraud must beequally connected. The Bangkok Blueprint provides a foundation for stronger cooperation and collective action to protect citizens and strengthen trust in the digital economy”, said Ekniti Nitithanprapas, Deputy Prime Minister and Finance Minister of Thailand.
By fostering a safer and more trusted financial ecosystem, the Blueprint seeks to help countries harness the full potential of digital finance to expand opportunity, inclusion and sustainable growth.
The 48-pages report analysed by Maverick News 30 – envisages that resilience to cyber-enabled fraud is also a precondition for confidence in the broader digital economy and for promoting and sustaining the development gains that it enables. Digital financial services are increasingly the gateway through which individuals and businesses receive income, make payments, save, borrow, insure against shocks, access public transfers, and participate in the broader digital economy. When cyber-enabled
fraud erodes trust, users may reduce participation in or abandon digital services and systems, limiting their benefits for financial inclusion and resilience for households and micro, small, and medium enterprises, as well as their contribution to job creation and economic growth.
To address these systemic challenges, this paper proposes a framework consisting of 12 key considerations (KCs) for a comprehensive national strategy to combat cyber-enabled fraud. It builds on the IMF–WBG Bali Fintech Agenda (IMF and WBG 2018), which established policy considerations for harnessing digital financial services while managing the risks, including safeguarding financial integrity
and fostering international cooperation.
Within their respective mandates, the blueprint will also help IMF and WBG staff develop their work on cyber-enabled fraud, inform their dialogue with national authorities, and shape their contributions to standard-setting bodies and other relevant international institutions. Although these KCs are directed primarily at the financial sector, the challenges they address are inherently broader. Cyber-enabled fraud frequently originates outside the financial sector, on social media, digital platforms, e-commerce sites, and telecommunications networks, where victims are first targeted, deceived, or recruited before any transaction reaches the financial system.
Financial sector measures alone are therefore necessary but not sufficient. Effective mitigation requires a whole-of-ecosystem response that engages non - financial actors, relevant authorities, platform operators, and telecommunications providers, so that prevention, detection, and response extend across the full chain through which fraud is perpetrated. The blueprint focuses mostly on financial sector stakeholders, with the understanding that they are part of a wider ecosystem.
Team Maverick.